Yes, NRIs and OCI cardholders can take a home loan in India to buy, build or renovate a residential property. Banks and housing finance companies lend up to 75–90% of the property value depending on the loan size, and the loan is disbursed and repaid in rupees. Under FEMA, EMIs must come from your NRE, NRO or FCNR account, from inward remittances through banking channels, or from rent on the property. You cannot simply pay the lender in dollars or dirhams.
Expect more paperwork than a resident loan, often shorter tenures and sometimes a slightly higher rate. Tax benefits are usually smaller than NRIs expect.
Who is eligible for an NRI home loan?
Each lender sets its own criteria, but typical requirements look like this:
| Criterion | Typical requirement (varies by lender) |
|---|---|
| Residential status | NRI (Indian passport holder living abroad) or OCI/PIO cardholder |
| Age | Usually 21+ at application; loan must end by around 60–70 depending on whether you are salaried or self-employed |
| Income abroad | A minimum annual income, often set by country or currency; Gulf-based applicants may see thresholds in AED |
| Work experience | Commonly 2–3 years total, with at least 6–12 months with the current overseas employer |
| Employment type | Salaried abroad is easiest; self-employed need audited accounts and more history; seafarers often have separate norms |
| Co-applicant | Some lenders require or prefer a resident close relative as co-applicant, especially for larger loans |
| Credit history | Indian credit score (CIBIL or similar) if you have one; some lenders ask for a credit report from your country of residence |
Minimum salary and work experience for an NRI home loan
Few lenders publish a single minimum salary, and those that do set it by country. Examples from official bank pages, October 2026:
| Lender | Minimum income | Work experience | Age |
|---|---|---|---|
| ICICI Bank | USD 42,000 a year (US and other countries); AED 84,000 a year (GCC); USD 24,000 a year (merchant navy) | At least 1 year of overseas employment (salaried); 3 years in the current business abroad (self-employed) | 21 to 65, or retirement age at loan maturity |
| SBI | Not published on its NRI home loan page | Not published on that page | 18 to 70; minimum loan ₹15 lakh |
| HDFC Bank | Not published; varies by employment type | Not published | Not published |
Lenders also look at how much of your income already goes on EMIs, so the minimum is a floor, not a guarantee. Third-party sites quote other banks' thresholds, but check them on the bank's own page or with its NRI desk.
Maximum tenure for an NRI home loan
RBI's rules say the loan amount, margin and repayment period for an NRI housing loan "shall be at par with those applicable to housing finance provided to a person resident in India". In practice lenders' published NRI tenures still differ:
- SBI: up to 30 years.
- ICICI Bank: up to 30 years.
- HDFC Bank: up to 20 years for NRIs, against up to 30 years (or until retirement, whichever is lower) for resident borrowers.
The age limits above also cap the tenure: a 45-year-old with a lender whose limit is 65 at maturity can get at most 20 years. A longer tenure lowers the EMI but raises total interest, which you can compare with the home loan calculator.
NRI home loan vs a regular home loan
| Feature | NRI home loan | Resident home loan |
|---|---|---|
| Loan-to-value limits | Same RBI limits (90%, 80%, 75% by loan size) | Same |
| Amount, margin, repayment period | "At par" with resident loans under RBI rules, though some lenders publish a shorter NRI tenure | Lender's standard terms |
| Repayment | Only by remittance from abroad, from NRE, FCNR(B) or NRO accounts, or from rent on the property | Any Indian account |
| Where the loan can go | For property in India; not credited to NRE or FCNR(B) accounts | For property in India |
| Income proof | Overseas salary slips, employment contract, overseas bank statements, tax forms (W-2, P60) or a country credit report, depending on the lender | Indian salary slips, Form 16, ITR |
| Being in India | Not required; lenders such as ICICI and HDFC allow a power of attorney for paperwork and disbursal | Not applicable |
The main practical differences are paperwork and how you repay. NRI rates are typically linked to a benchmark: HDFC Bank, for example, quoted its NRI rate as the repo rate plus 2.50% to 7.95% (7.75% to 13.20%) in October 2026. Compare the spread you are actually offered.
Home loans for OCI cardholders
OCI cardholders can borrow on the same footing as NRIs. FEMA's borrowing and lending regulations say a bank "may grant loan to a NRI/OCI Cardholder" to acquire a residential home in India, and housing finance companies may lend to NRIs and OCI cardholders too. The property rules are also the same: an NRI or OCI can buy any immovable property in India "other than agricultural land/plantation property/farm house". Some lenders accept Form 97 instead of a PAN card from OCI customers who do not have a PAN, but you will need a PAN for property tax and capital-gains purposes later.
These rupee housing loans are for property in India. An Indian bank's NRI home loan cannot be used to buy a home in Dubai or elsewhere abroad; for that you would need a lender in that country.
Which lenders offer NRI home loans?
Rather than chasing a "best bank" list, look at the lender type and how well it serves NRIs:
- Public and private sector banks: Generally the most competitive rates, linked to an external benchmark such as the RBI repo rate. Useful if you already bank with them for NRE/NRO accounts. Many have NRI desks or overseas representative offices.
- Housing finance companies (HFCs): Regulated by the RBI (with the National Housing Bank supervising parts of the sector). They can be more flexible on documentation, self-employed income or under-construction properties, sometimes at a higher rate.
- Builder-tied lenders: Convenient for pre-approved projects, but compare rate and fees independently.
Compare the spread over the benchmark, fees, maximum NRI tenure and how easily you can service the loan from abroad.
How much can you borrow? Loan-to-value (LTV) limits
RBI caps how much of the property value a bank can lend. These limits apply to NRIs the same way as residents:
| Loan amount | Maximum LTV | Minimum own contribution |
|---|---|---|
| Up to ₹30 lakh | 90% | 10% |
| Above ₹30 lakh up to ₹75 lakh | 80% | 20% |
| Above ₹75 lakh | 75% | 25% |
The property value for LTV purposes generally excludes stamp duty and registration charges, so budget for these separately (they vary by state, commonly 5–8% of the value). Your down payment and these costs must come from your own funds, typically your NRE/NRO account or fresh remittances. Your actual loan will also be limited by your repayment capacity: lenders usually cap total EMIs at a percentage of your net monthly income. To see how much you could borrow, try our NRI home loan eligibility calculator.
Debt-to-income ratio (FOIR): how much of your pay can go on EMIs
Indian banks size a home loan by your debt-to-income ratio, which they call FOIR (fixed obligations to income ratio). It is every EMI you pay, including the new home loan, divided by your monthly take-home pay. SBI calls the same test the EMI/NMI ratio, where NMI is net monthly income after tax and payroll deductions, and HDFC Bank asks NRIs to enter net rather than gross income in its eligibility calculator.
FOIR = (existing EMIs + new home loan EMI) ÷ monthly take-home pay × 100
Illustrative example: you take home US$4,000 a month in the US and pay a US$600 car loan EMI. At ₹96/US$ that is ₹3,84,000 of income and ₹57,600 of existing EMIs, so your FOIR is already 15%. Adding an ₹80 lakh loan at 8.75% over 20 years (EMI ₹70,697, as in the worked example below) would take it to about 33%.
Turn it around to see the most you could borrow. If a bank allowed 40% of take-home pay for all EMIs, that is ₹1,53,600 a month, leaving ₹96,000 for the new EMI after the car loan. At 8.75% over 20 years that supports about ₹1.09 crore. At 60%, the room is ₹1,72,800 and the loan about ₹1.96 crore. The RBI loan-to-value limits above still apply, and you get the lower of the two amounts.
What limit will a bank use? Each bank sets its own. SBI's home loan FAQ says its EMI/NMI ratio ranges from 20% to 70% depending on your net annual income slab, with higher earners allowed a bigger share (checked 6 October 2026). HDFC Bank's and ICICI Bank's NRI pages don't publish a figure; they say eligibility depends on income, existing obligations and repayment capacity. Clearing a car or personal loan before you apply helps directly, because every rupee of EMI you drop is a rupee of room for the home loan EMI. The eligibility calculator linked above lets you set the limit yourself.
NRI home loan process, step by step
You can do almost all of it from abroad. The order is eligibility, documents, sanction, property and legal checks, then disbursement, with a power of attorney holder in India covering anything that needs a signature in person.
1. Check your eligibility
Make sure you meet the lender's age, income and work-experience rules (see the eligibility table above) and that the property is residential. Some lenders also want a credit report from your country of residence. ICICI Bank asks for one, no older than 45 days, from NRI and OCI applicants in 16 countries, including the US, UK, UAE, Canada, Australia and Singapore.
2. Apply and send your documents
Apply online or through the bank's NRI desk, and upload your KYC and income documents (listed in the next section). ICICI Bank's online application has five steps: income details, review the offer, pay the processing fee, upload documents, then download a provisional sanction letter. HDFC Bank takes the processing fee by cheque from your NRE or NRO account. You don't need to have chosen a property yet: HDFC Bank says you can apply before you have selected one.
3. Get the sanction
The sanction letter sets out the amount, rate and tenure the bank will lend, subject to the property passing its checks. ICICI Bank's sanction letter is valid for 6 months (180 days) from the date of issue. None of the banks we checked publishes a timeline for the whole process. ICICI says it depends on how quickly documents are submitted and verified.
4. Property and legal checks
Once you pick a property, the bank checks the title (legal verification) and values the property (technical verification) before it pays anything out. The property is then mortgaged to the bank. RBI rules require an NRI housing loan to be fully secured by an equitable mortgage of the property being bought.
5. Disbursement
The bank pays the seller or builder in India after you have paid your own contribution. For an under-construction flat, money is released in stages as construction progresses. The loan amount can't be credited to your NRE or FCNR(B) account.
If you are abroad: the power of attorney
ICICI Bank says a PoA is needed only if an applicant or co-applicant can't come to India for the disbursement formalities, and that it has to be signed before disbursement, not at application. ICICI Bank and HDFC Bank both require the PoA in their own format. At ICICI the holder can be a family member, friend or neighbour living in India. The power of attorney section below covers attestation and stamping.
Repaying from abroad
EMIs are paid in rupees from your NRE or NRO account. ICICI Bank, for example, says NRI home loan EMIs are repaid from an NRE or NRO account only. Put the mandate on the account you will keep topped up by remittance. The full list of permitted repayment sources is in the FEMA section below.
Documents you will need
- Identity and status: Passport, valid visa or work/residence permit (or OCI card), PAN card, overseas address proof, photographs.
- Income: Employment contract or employer letter, recent salary slips (often 3–6 months), overseas bank statements showing salary credits, and tax returns or equivalent (for example W-2 and Form 1040 in the US, P60 in the UK). Self-employed: business registration and audited financials for 2–3 years.
- Indian accounts: NRE/NRO statements for 6 months.
- Credit: Indian credit report if available; some lenders ask for a report from your country of residence.
- Property: Sale agreement, title documents, approved plan, builder's NOC and allotment letter for under-construction flats, receipts for amounts already paid.
- Power of attorney (if applicable): See below.
RBI and FEMA rules for NRI home loans
Three sets of rules apply. FEMA's Borrowing and Lending Regulations, 2018 say who may lend to an NRI or OCI and for what. The RBI's Master Direction on rupee borrowing and lending with NRIs sets the terms of a housing loan. And the RBI's Credit Facilities Directions for banks cap how much they can lend against a home. In short:
- Who can lend: a bank may lend to an NRI or OCI cardholder to buy a residential home in India, and a registered housing finance company may give NRIs and OCIs housing loans on the RBI's terms (FEMA 3(R)/2018-RB, Regulation 7, amended up to 16 February 2026).
- What for: a residential home in India. Borrowed money can't be used for agricultural or plantation activities, real estate business or building farmhouses, which the regulations list as "restricted end uses". NRIs and OCIs also can't buy agricultural land, plantation property or a farmhouse in the first place.
- Same terms as residents: the loan amount, margin money and repayment period must be "at par" with housing loans to residents (RBI FEMA Master Direction No. 6/2015-16, updated 8 September 2026). The RBI doesn't set a maximum tenure, so each lender sets its own. That is why SBI and ICICI Bank offer up to 30 years and HDFC Bank 20 years to NRIs.
- Security: the loan must be fully secured by an equitable mortgage of the property bought, and if needed by a lien on your other assets in India.
- Loan-to-value caps: 90% for loans up to ₹30 lakh, 80% above ₹30 lakh and up to ₹75 lakh, and 75% above ₹75 lakh (RBI Credit Facilities Directions, 2025, paragraph 111, updated 1 October 2026). Banks can't add stamp duty, registration and documentation charges to the property cost, except for homes costing up to ₹10 lakh.
- Interest rate: banks must link floating-rate home loans to an external benchmark, such as the RBI repo rate or a Treasury Bill yield, and reset the rate at least once every three months (RBI Interest Rates on Advances Directions, 2025).
- Refinancing or switching lender: the rules have no separate regime for moving an NRI home loan, so the new loan has to meet the same conditions. Banks do offer it. ICICI Bank allows a balance transfer of an existing NRI home loan, with an optional top-up, subject to eligibility.
The permitted repayment sources are covered in the next section.
Repayment rules under FEMA
Under the FEMA borrowing and lending regulations and the RBI's related Master Direction, a housing loan to an NRI or OCI is given in rupees and the disbursement goes to the seller or builder in India. It cannot be credited to your NRE or FCNR account or taken abroad. Repayment can be made through:
- Debit to your NRE, NRO or FCNR(B) account,
- Inward remittance from abroad through normal banking channels,
- Rental income from the property itself, and
- In some cases, payments by close relatives in India from their own bank accounts.
The loan is always repaid in rupees. In practice, set up a standing instruction or e-mandate on your NRE account and top it up by remittance each month. If you use NRE funds, the money is fully repatriable up to that point, which matters later if you sell. Our guide to NRE vs NRO accounts explains which account to use, and repatriating money from India covers taking sale proceeds back.
Note also that NRIs and OCIs can buy residential and commercial property but not agricultural land, plantation property or farmhouses, and lenders will not finance these.
Power of attorney
You can do most of the loan process remotely, but registration and some bank formalities need a physical signature in India. A specific power of attorney (PoA) to a trusted relative solves this.
- Keep it specific: limit it to buying the named property, signing the loan documents and registration.
- Sign it abroad in front of an Indian consulate officer or a notary, and get it apostilled if your country is a Hague Convention member.
- Once it reaches India, it usually needs to be adjudicated and stamped with the state's stamp authority within a set time (often three months).
NRI home loan interest rates (October 2026)
Three of the four banks below point NRIs to their normal home loan card rate, so the NRI home loan rate is the same range residents see. HDFC Bank is the exception: it publishes a separate NRI rate with a much wider range. These figures are from each bank's own website, checked on 9 October 2026:
| Bank | Published floating rate | Linked to | Where the NRI rate comes from |
|---|---|---|---|
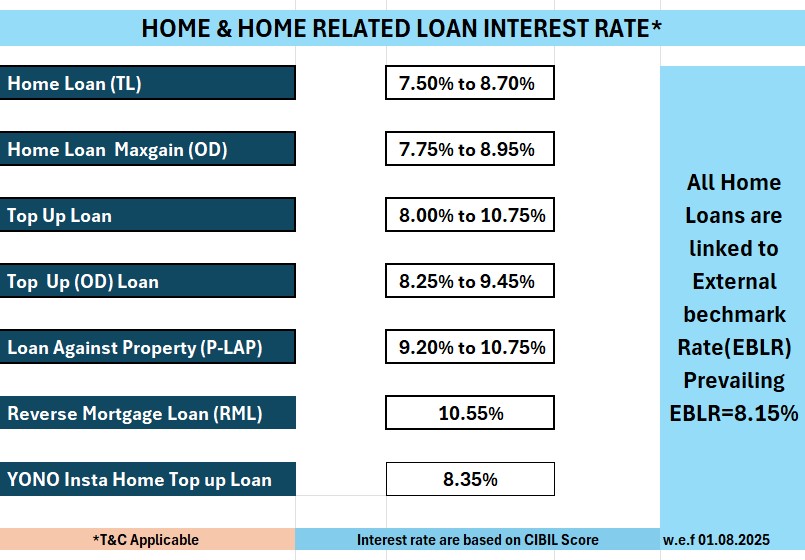
| SBI | 7.25% to 8.55% | EBLR (external benchmark lending rate), shown as 7.90% | Its NRI home loan page links to the general home loan card rate, effective 20 May 2026 |
| HDFC Bank | 7.75% to 13.20% (repo rate + 2.50% to 7.95%) | RBI policy repo rate, shown as 5.25% | A separate NRI rate on its NRI home loan page; no date given |
| ICICI Bank | 8.75% to 9.90% salaried; 8.75% to 10.05% self-employed | Repo rate, shown as 5.50% from 8 October 2026 | Its NRI home loan FAQ sends NRI and OCI customers to its standard home loan rate page |
| Bank of Baroda | 7.20% to 8.95% (BRLLR minus 0.70% to BRLLR plus 1.05%) | Baroda Repo Linked Lending Rate (BRLLR), reset monthly | Its NRI home loan page says its rates have no differentiation for NRIs; no date given |
Where you land in each range depends mostly on your credit score and loan size, and at ICICI Bank on whether you are salaried or self-employed. Axis Bank also lends to NRIs, but its NRI home loan page doesn't publish a rate, so it isn't in the table.
Check the date on any rate you are quoted. The RBI raised the repo rate by 0.25% to 5.50% on 7 October 2026. ICICI Bank's page already uses the new repo rate. When we checked, HDFC Bank's page still showed the old 5.25%, SBI's card rate dated from May 2026 and Bank of Baroda's page carried no date, so expect their figures to move up. RBI rules make banks reset repo-linked and other externally benchmarked loans at least once every three months, so existing borrowers feel the change too. On the ₹80 lakh, 20-year loan in the worked example below, a 0.25% rise adds about ₹1,300 to the monthly EMI.
How much could you borrow at these rates? Enter your overseas take-home pay, existing EMIs (in India and abroad) and a rate from the table into the NRI home loan eligibility calculator to see a loan amount and EMI before you talk to a bank.
Interest rates for NRIs
NRI home loan rates are usually close to resident rates, sometimes the same and sometimes slightly higher, depending on the lender, your credit profile and the loan size. Most bank loans are floating-rate and linked to an external benchmark, so your EMI or tenure will change when the RBI moves the repo rate. Some lenders also cap NRI tenures at 15–20 years against up to 30 years for residents, which raises the EMI. Check the current rate card on the day you apply, and ask what spread over the benchmark applies to you.
Good news on prepayment: RBI rules prohibit foreclosure or prepayment penalties on floating-rate loans to individuals (for non-business purposes), so you can prepay from NRE funds without charges. Fixed-rate loans may carry penalties.
Worked example: EMI and total cost
Priya lives in Dubai and is buying a ₹1.1 crore flat in Hyderabad. Because a loan above ₹75 lakh is capped at 75% LTV, she borrows ₹80 lakh (about 73%) and pays ₹30 lakh plus stamp duty and registration from her NRE account.
| Scenario | Monthly EMI | Total interest paid |
|---|---|---|
| ₹80 lakh, 8.75%, 20 years | ₹70,697 (about AED 2,700 or US$735) | ₹89.7 lakh |
| ₹80 lakh, 8.75%, 15 years | ₹79,956 | ₹63.9 lakh |
| ₹80 lakh, 8.50%, 20 years | ₹69,426 | ₹86.6 lakh |
Two things stand out. First, choosing 15 years instead of 20 costs about ₹9,300 more a month but saves roughly ₹26 lakh of interest. Second, a 0.25% lower rate saves about ₹3 lakh over 20 years, so negotiating the spread is worth an email or two. In the first year of the 20-year loan, about ₹6.94 lakh of her EMIs is interest and only ₹1.54 lakh reduces the principal.
The rate of 8.75% is only an illustration, and the currency conversions assume about ₹96/US$ and ₹26/AED (late September 2026). Plug in your own numbers with our home loan EMI calculator.
Tax benefits for NRIs (FY 2026-27)
NRIs can claim home loan deductions in India, but only against taxable Indian income, and most of them only under the old regime.
- Interest (section 22(2) of the Income-tax Act, 2025, formerly Section 24(b)): For a self-occupied or vacant property, interest up to ₹2 lakh a year is deductible under the old regime only. For a let-out property, the full interest is deductible against the rental income. Pre-construction interest is claimed in five equal instalments after completion.
- Principal (section 123, formerly Section 80C): Up to ₹1.5 lakh a year (shared with other 80C items), including stamp duty and registration in the year paid. Old regime only.
- Loss from house property: Under the old regime, up to ₹2 lakh of loss can be set off against other Indian income each year, and the rest carried forward for eight years against future house property income. Under the new regime, a let-out property's interest can reduce its own rent to nil, but the excess loss cannot be set off against other income.
Back to Priya. If she lets the flat for ₹30,000 a month (₹3.6 lakh a year), the taxable rent after the 30% standard deduction is ₹2.52 lakh. Year-one interest of ₹6.94 lakh turns this into a loss of ₹4.42 lakh. Under the old regime she can set off up to ₹2 lakh against other Indian income, such as NRO interest, and carry forward the rest. With no other Indian income, the 80C principal deduction adds nothing, because her taxable income is already nil. The tenant must still deduct TDS on rent paid to an NRI, so she should consider applying for a lower-deduction certificate. UAE residents pay no tax on this at home. US or UK residents must also report the rent there and claim credit under the relevant tax treaty.
The Income-tax Act, 2025 took effect on 1 April 2026 and renumbers these provisions: 24(b) is now section 22(2), 80C is section 123, TDS on payments to non-residents (195) is section 393(2), and lower-deduction certificates (197, Form 13) are section 395 with Form 128. The limits are unchanged. Confirm your position with a CA.
Prepay the loan or invest the surplus?
Once the loan is running, many NRIs wonder whether to send extra money to prepay it or invest it. The usual comparison is the post-tax loan rate against the post-tax expected return. For NRIs there is a currency angle too. If you earn in dollars and the rupee keeps weakening against the dollar at its long-run pace, your rupee loan gets cheaper in dollar terms each year, which reduces the real cost of carrying it. On the other hand, guaranteed interest savings at 8–9% are hard to beat with low-risk investments. Our deeper analysis of home loan prepayment vs SIP walks through the trade-off.
What happens when you return to India?
- Tell the lender: Your loan account is updated to resident status and your NRE/NRO accounts are redesignated. The loan continues; the lender may review the rate or terms.
- Switch the repayment source: Move the EMI mandate to your resident savings account once your Indian salary starts. If you need new credit after the move, see loans after returning to India.
- Tax deductions become useful: With Indian salary income, the interest and principal deductions (old regime) and the loss set-off can finally reduce your tax. Plan the regime choice with this in mind. During RNOR years your foreign income may still be outside Indian tax; see RNOR status explained.
Loans for NRIs who have returned to India
Once you move back, you borrow as a resident: the bank assesses you on its normal resident terms and your Indian income. Three situations come up:
- Converting the NRI loan you already have: tell the lender about your change of status. HDFC Bank, for example, reassesses repayment capacity "based on Resident status", works out a revised repayment schedule and moves the outstanding balance to its current resident rate for that product. It gives you a letter confirming the change.
- A new home loan as a resident: you apply like any resident borrower, with Indian income proof such as salary slips, Form 16 and ITRs. The RBI loan-to-value caps above stay the same.
- Loan against property (LAP): if you already own a home in India, a LAP lets you borrow against it for other needs, but it costs more than a home loan. SBI's card rate for its property loan (P-LAP) is 8.95% to 10.50%, against 7.25% to 8.55% for its home loan (both effective 20 May 2026, before the October repo rise).
None of the banks' pages we checked says how it weighs your foreign income history once you are a resident, beyond HDFC Bank's note that it reassesses you on resident status. Our guide to loans after returning to India covers building an Indian credit score in your first year back and what each lender asks for.
Common mistakes
- Borrowing to the limit of LTV without budgeting stamp duty and registration, which can add 5–8% in cash.
- Paying EMIs from NRO without thinking about repatriation. NRE-funded payments keep future sale proceeds more easily repatriable.
- Assuming tax benefits will offset the interest. With no Indian income, deductions are worth close to nothing.
- A vague, general power of attorney, or one in a format the bank or sub-registrar rejects; many banks have their own template.
- Ignoring currency risk. A job loss abroad or a strong rupee phase can make the EMI harder to service. Keep 6–12 months of EMIs as a buffer.
- Not insuring the loan. A term policy covering the outstanding loan is usually far cheaper than the lender's bundled loan-protection plan. See our guide to NRI term insurance.
- Buying without checking whether you should own at all. Renting in India while investing the difference can be better if your return date is uncertain; try the rent vs buy calculator.
NRI home loan checklist
- Check eligibility: age, income, experience, and whether you need a co-applicant.
- Get your Indian credit report, and your foreign credit report if the lender asks.
- Confirm the property is residential or commercial, not agricultural land or a farmhouse, and that the title is clean.
- Arrange down payment plus stamp duty and registration from NRE/NRO or remittance.
- Compare lenders on spread, fees, tenure and NRI servicing, not just the headline rate.
- Execute a specific power of attorney in the lender's accepted format, attested and apostilled.
- Set up an e-mandate on your NRE account and keep an EMI buffer.
- Take term cover at least equal to the outstanding loan.
- If you let the property, apply for a lower TDS certificate and file an Indian return.
Bottom line
An NRI home loan works much like a resident one: the same LTV limits, similar rates, and rupee repayments that must flow through NRE, NRO, FCNR or remittance. The biggest differences are paperwork, the power of attorney, and the fact that Indian tax benefits only help if you have Indian income. Size the loan to your EMI comfort, not the lender's maximum, and remember that if you later sell, our guide to selling property in India as an NRI covers TDS and capital gains.
A home in India touches cash flow, currency, insurance and return plans at once. Our NRI planning hub brings these together so you can see whether the purchase fits your wider goals. This article is general information, not personalised advice; confirm your situation with a CA or tax advisor. When you are ready, build your complete NRI plan around the loan.