To retire in India at 60, you need about 26 times your yearly spending at that point. For a household spending ₹50,000 a month today, that is about ₹1.6 crore in today's money, or ₹5.1 crore on the day you retire if you are 40 now. A couple in their own home in a tier-2 city spending ₹30,000 a month needs about ₹95 lakh in today's money. A metro family spending ₹1 lakh a month needs about ₹3.2 crore.
Earning or saving outside India? When part of your money is in dollars, dirhams or pounds, the maths changes; the NRI retirement guide covers that case.
The rest of this guide shows the tables for people aged 30, 40 and 50, what to invest each month to get there, and what EPF, PPF, NPS, rent and healthcare do to the number. To run it with your own figures, use FinPlann's retirement corpus calculator.
All figures are illustrative, not a forecast. They assume your spending is stated in today's rupees, inflation is 6% a year, your money earns 7% a year after you retire, it has to last until age 90, and you withdraw each year's spending at the start of that year. Living abroad and planning to move back? Read the guide for NRIs retiring in India, which uses the same method.
How much money is enough to retire in India? A quick answer by city and spend
Your monthly spending matters far more than any other input, and where you live drives most of it. The households below are examples to help you find your row. Your own budget beats any city average.
| Example household | Monthly spend today | Needed to retire at 60, in today's ₹ | Needed to retire at 55, in today's ₹ | At 60, if you are 40 now |
|---|---|---|---|---|
| Own home, smaller or tier-2 city, simple lifestyle | ₹30,000 | ₹95 lakh | ₹1.1 crore | ₹3.0 crore |
| Own home, tier-2 city, comfortable | ₹50,000 | ₹1.6 crore | ₹1.8 crore | ₹5.1 crore |
| Own home in a metro | ₹75,000 | ₹2.4 crore | ₹2.7 crore | ₹7.6 crore |
| Metro, travel and domestic help | ₹1,00,000 | ₹3.2 crore | ₹3.6 crore | ₹10.1 crore |
| Metro, renting, frequent travel | ₹1,50,000 | ₹4.7 crore | ₹5.4 crore | ₹15.2 crore |
Illustrative. 6% inflation, 7% return after retirement, money lasting to 90.
"In today's money" is the corpus divided back by inflation, so you can compare it with prices you know. It is the same target as the bigger number in the last column, seen from today. If you are 40, ₹5.1 crore at 60 buys roughly what ₹1.6 crore buys now.
Worked tables: age 30, 40 and 50, retiring at 55 or 60
Find your age today, the age you want to stop working, and your monthly spend in today's rupees.
| Age today | Retire at | Monthly spend today | Monthly spend in the first retired year | Corpus needed at retirement | Same corpus in today's ₹ |
|---|---|---|---|---|---|
| 30 | 55 | ₹30,000 | ₹1.29 lakh | ₹4.6 crore | ₹1.1 crore |
| 30 | 55 | ₹50,000 | ₹2.15 lakh | ₹7.7 crore | ₹1.8 crore |
| 30 | 55 | ₹1,00,000 | ₹4.29 lakh | ₹15.4 crore | ₹3.6 crore |
| 30 | 60 | ₹30,000 | ₹1.72 lakh | ₹5.4 crore | ₹0.95 crore |
| 30 | 60 | ₹50,000 | ₹2.87 lakh | ₹9.1 crore | ₹1.6 crore |
| 30 | 60 | ₹1,00,000 | ₹5.74 lakh | ₹18.1 crore | ₹3.2 crore |
| 40 | 55 | ₹30,000 | ₹71,900 | ₹2.6 crore | ₹1.1 crore |
| 40 | 55 | ₹50,000 | ₹1.20 lakh | ₹4.3 crore | ₹1.8 crore |
| 40 | 55 | ₹1,00,000 | ₹2.40 lakh | ₹8.6 crore | ₹3.6 crore |
| 40 | 60 | ₹30,000 | ₹96,200 | ₹3.0 crore | ₹0.95 crore |
| 40 | 60 | ₹50,000 | ₹1.60 lakh | ₹5.1 crore | ₹1.6 crore |
| 40 | 60 | ₹1,00,000 | ₹3.21 lakh | ₹10.1 crore | ₹3.2 crore |
| 50 | 55 | ₹30,000 | ₹40,100 | ₹1.4 crore | ₹1.1 crore |
| 50 | 55 | ₹50,000 | ₹66,900 | ₹2.4 crore | ₹1.8 crore |
| 50 | 55 | ₹1,00,000 | ₹1.34 lakh | ₹4.8 crore | ₹3.6 crore |
| 50 | 60 | ₹30,000 | ₹53,700 | ₹1.7 crore | ₹0.95 crore |
| 50 | 60 | ₹50,000 | ₹89,500 | ₹2.8 crore | ₹1.6 crore |
| 50 | 60 | ₹1,00,000 | ₹1.79 lakh | ₹5.6 crore | ₹3.2 crore |
Illustrative. 6% inflation, 7% return after retirement, money lasting to 90, withdrawals at the start of each year.
Look at the last column. In today's money the target depends only on your spending and your retirement age, not on how old you are now. A 30-year-old and a 50-year-old who both spend ₹50,000 and retire at 60 need the same ₹1.6 crore in today's rupees. The 30-year-old's figure looks bigger (₹9.1 crore against ₹2.8 crore) only because prices have 30 years to rise instead of 10.
Retiring at 55 instead of 60 needs more in today's money, because the corpus has to last 35 years instead of 30. The easiest mistake is planning with today's numbers. ₹50,000 a month becomes ₹2.87 lakh a month after 30 years of 6% inflation. That is not a richer life, just the same one at future prices.
How much should you have saved by 40?
Use the age-40 rows above rather than a multiple of salary. Illustrative: if you are 40, spend ₹50,000 a month and want to retire at 60, you need ₹5.1 crore. About ₹75 lakh invested today would get there on its own at 10% a year, with no further SIP. That is the "on track" figure at 40. For a ₹30,000 household it is about ₹45 lakh, and for ₹1 lakh a month about ₹1.5 crore.
Most people at 40 have less, and that is fine as long as the SIP makes up the rest. With ₹25 lakh already saved, the ₹50,000 household needs about ₹46,600 a month instead of ₹69,800; with ₹50 lakh, about ₹23,400. Count EPF, NPS and money kept only for retirement. Leave out the emergency fund and savings for children's goals.
How much do you need to invest each month?
If you are starting from zero, here is the monthly SIP that builds the corpus above by your retirement date. It assumes 10% a year before retirement, which is an assumption for a mix of equity and debt, not a promise.
| Age today | Retire at | ₹30,000 a month | ₹50,000 a month | ₹1,00,000 a month |
|---|---|---|---|---|
| 30 | 55 | ₹37,200 | ₹62,100 | ₹1.24 lakh |
| 30 | 60 | ₹26,100 | ₹43,500 | ₹87,100 |
| 40 | 55 | ₹64,400 | ₹1.07 lakh | ₹2.15 lakh |
| 40 | 60 | ₹41,900 | ₹69,800 | ₹1.40 lakh |
| 50 | 55 | ₹1.87 lakh | ₹3.12 lakh | ₹6.24 lakh |
| 50 | 60 | ₹84,100 | ₹1.40 lakh | ₹2.80 lakh |
Illustrative. Flat monthly SIP, invested at the start of each month, 10% a year before retirement. Ignores money you have already saved.
Two things bring these numbers down. Any EPF, PPF or mutual fund savings you already have reduce the target, as covered below. And if you raise your SIP as your salary grows, the first year's amount can be lower than this table. Starting at 50 is where the maths gets hard: retiring at 55 then needs ₹3.12 lakh a month for the ₹50,000 household, more than six times what it spends.
If you're in your 30s: a checklist
Your 30s are when each rupee saved does the most work, because it has the longest to compound. Illustrative: a ₹10,000 monthly SIP started at 30 and kept going to 60 grows to about ₹2.1 crore at 10% a year. Started at 40, the same SIP reaches about ₹72 lakh. The extra ten years cost ₹12 lakh more in contributions (₹36 lakh against ₹24 lakh) and add about ₹1.4 crore at 60. Same assumptions as the SIP table above: 10% a year for 30 or 20 years, invested at the start of each month.
| Action | When |
|---|---|
| Work out your retirement number from your spending, using the tables above or the retirement corpus calculator | This month |
| Start a retirement SIP that is separate from your goal SIPs, and raise it when your salary rises | This month |
| Check your EPF is active in your UAN passbook, and decide whether a VPF top-up suits you | Next 3 months |
| If you file under the old regime, decide whether NPS Tier 1 is worth it for the extra ₹50,000 deduction under section 124(3) | Next 3 months |
| Buy term insurance; FinPlann's guide on how much term cover you need helps size it | Now |
| Buy a family floater health policy while everyone is healthy (see healthcare costs below) | Now |
| Write a simple will and add nominees to every account | Next 6 months |
| Review your number and your SIP | Every year |
If you do only two things this month, work out your number and start the separate retirement SIP.
Why the 25x rule falls short in India
The 25x rule says you need 25 times your first year's spending, which is the same as withdrawing 4% in year one. It comes from 1990s US research on US stocks and bonds over 30-year retirements. In India, your money earns only about 1% a year more than inflation under these assumptions, so the multiple needs to be higher:
- Retire at 60, money lasting 30 years: 26.3 times first-year spending, a 3.8% first-year withdrawal
- Retire at 55, money lasting 35 years: 30 times, a 3.3% first-year withdrawal
For a 40-year-old spending ₹50,000 a month, the 25x rule says ₹4.8 crore at 60, against ₹5.1 crore needed. Retire at 55 and it says ₹3.6 crore, against ₹4.3 crore needed. The earlier you stop, the wider the gap. If you want to stop in your 40s, the FIRE calculator is built for that.
What if inflation or returns are different?
6% is a planning assumption. It sits at the top of the RBI's 2% to 6% tolerance band, and CPI inflation has run both below and above it in recent years. Here is the 40-year-old, ₹50,000-a-month, retire-at-60 case under other assumptions:
| Change | Corpus needed at 60 |
|---|---|
| Base case: 6% inflation, 7% return, money lasting to 90 | ₹5.1 crore |
| Inflation 5% | ₹3.7 crore |
| Inflation 7% | ₹7.0 crore |
| Return 8% after retirement | ₹4.5 crore |
| Return 6% after retirement | ₹5.8 crore |
| Money lasting to 85 | ₹4.3 crore |
| Money lasting to 95 | ₹5.8 crore |
One point of inflation moves the answer by about ₹1.4 to 1.9 crore. One point of return moves it by about ₹0.6 to 0.7 crore. If you want a safety margin, plan with a higher inflation figure rather than hoping for a higher return.
What counts towards your retirement corpus: EPF, PPF and NPS
The corpus is money you can draw on to pay bills. Count it; don't count things you will live in or have promised to someone else.
Counts:
- EPF. The rate for FY 2025-26 is 8.25%, ratified by the Finance Ministry in June 2026, and EPFO declares it every year. As an illustration, ₹10 lakh in EPF at 40 grows to about ₹49 lakh by 60 at 8.25% with no new contributions. Your UAN passbook shows your balance.
- PPF. 7.1% for October to December 2026, unchanged since April 2020 and reviewed every quarter. ₹1.5 lakh a year for 15 years at 7.1% grows to about ₹40.7 lakh. If an account matures long before you retire, see FinPlann's roadmap for deploying a PPF or FD maturity in your 40s.
- NPS. Since PFRDA's December 2025 amendments, non-government subscribers can take up to 80% as a lump sum at exit and must use at least 20% to buy an annuity. Only 60% of the corpus is tax-free. The annuity becomes pension income, so it reduces how much you need to withdraw rather than adding to the lump sum. Under the old tax regime, you can deduct up to ₹50,000 a year extra under section 124(3) of the Income-tax Act, 2025 (old 80CCD(1B)).
- Mutual funds, shares, FDs, bonds and rental income from a second property.
Doesn't count: the home you live in, jewellery you will keep, your emergency fund (size it with the emergency fund calculator), and money set aside for children's education or weddings. Those are separate goals.
FinPlann's comparison of NPS and EPF for retirement covers how the two differ on returns, lock-in and tax.
Healthcare costs in retirement
Healthcare costs in India typically rise faster than general inflation, and they are the hardest part of a retiree's budget to cut. Suppose ₹5,000 of a ₹50,000 monthly budget is health spending. If that part rises at 10% a year instead of 6%, the corpus a 40-year-old needs at 60 goes from ₹5.1 crore to ₹6.4 crore, about 27% more. The 10% is an assumption to show the effect, not a measured rate.
Insurance keeps one bad year from draining the corpus. Buy a family floater while you are healthy, since policies bought later come with higher premiums and waiting periods for existing conditions. Under the old tax regime, premiums for senior citizens are deductible up to ₹50,000 a year under section 126 (old 80D). FinPlann's guide on how much health insurance an Indian family needs helps you size the cover, and the premiums belong in your monthly spend.
A paid-off home vs renting in retirement
If you will still pay rent after you stop working, it is part of your spending for 30 years, and it needs its own corpus. Here is the extra amount needed at 60, assuming rent rises at 6% a year:
| Rent today | Extra at 60 if you are 30 now | If you are 40 now | If you are 50 now | In today's ₹ |
|---|---|---|---|---|
| ₹15,000 a month | ₹2.7 crore | ₹1.5 crore | ₹85 lakh | ₹47 lakh |
| ₹25,000 a month | ₹4.5 crore | ₹2.5 crore | ₹1.4 crore | ₹79 lakh |
| ₹40,000 a month | ₹7.2 crore | ₹4.0 crore | ₹2.3 crore | ₹1.26 crore |
Illustrative. Same assumptions as the main table.
That is why owning your home by retirement makes such a difference to the number. It does not mean buying is always better. A home loan has costs too, and FinPlann's buy vs rent guide works through the trade-off. Just don't assume rent disappears when your salary does.
Is ₹1 crore enough to retire in India?
For most people retiring years from now, no. ₹1 crore at 60 is worth about ₹31 lakh in today's money if you are 40 now, and about ₹17 lakh if you are 30. At 6% inflation and 7% returns it lasts:
- about 9 years at ₹30,000 a month (in today's money) for someone 40 now, and about 6 years at ₹50,000
- about 17 years at ₹30,000 for someone 50 now, and about 10 years at ₹50,000
For someone retiring at 60 today, it depends on spending. ₹1 crore lasts about 24 years at ₹40,000 a month, 19 years at ₹50,000 and 15 years at ₹60,000. At ₹30,000 a month it lasts past 90. That can work with a paid-off home, health cover and a pension alongside it. It is tight for anyone who could live into their 90s.
How much net worth is considered rich in India?
There is no official line for "rich". The closest regulatory marker is SEBI's accredited investor test for individuals: an annual income of at least ₹2 crore, or a net worth of at least ₹7.5 crore with at least ₹3.75 crore in financial assets, or ₹1 crore of income plus ₹5 crore of net worth with at least ₹2.5 crore in financial assets.
Being rich and having enough to retire are different questions. Under the assumptions on this page, ₹7.5 crore of investments lets someone retiring at 60 today spend about ₹2.4 lakh a month for life. But a 30-year-old metro family spending ₹1 lakh a month needs ₹18.1 crore at 60, because of inflation. A net worth that sounds rich today may only be enough later.
Turning the corpus into a monthly income
Once you retire, you draw from the corpus each month. A common approach is to keep a few years of spending in debt funds or deposits and the rest in a mix that can still beat inflation, then withdraw through a systematic withdrawal plan. The SWP calculator with inflation shows how long a given corpus lasts when your monthly withdrawal rises with prices each year.
The order is simple: price your retirement life in today's rupees, inflate it to your retirement year, size the corpus to last to 90, then subtract what EPF, PPF and NPS will already provide. FinPlann's retirement corpus calculator does all four steps with your own numbers.
Retirement corpus at a glance
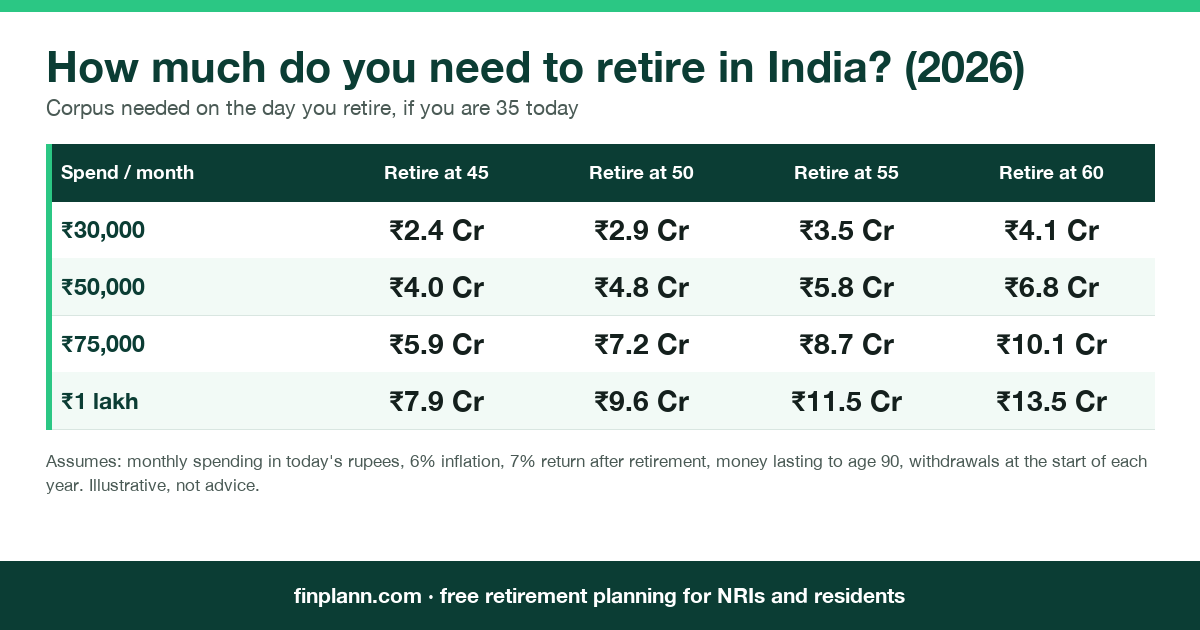
The corpus you need on the day you retire, if you are 35 today, by monthly spending in today's rupees. It uses the same assumptions as the tables above: 6% inflation, a 7% return after retirement and money lasting to age 90. Illustrative, not advice.